
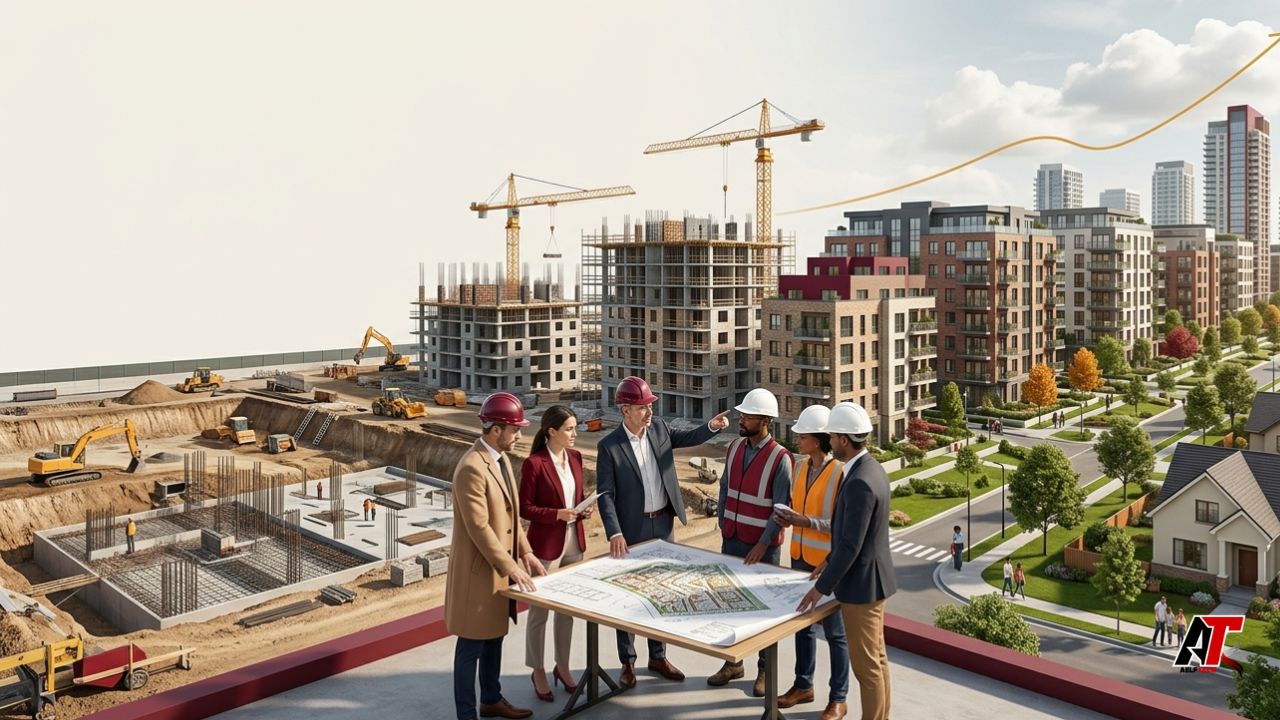
Housing development can create wealth in ways that buying an already-completed property cannot. A well-selected project may generate value as land gains planning certainty, construction progresses, homes are completed, and an operating asset begins producing income. That layered value-creation process is why institutions, private investors, family offices, and property companies often consider housing development projects as part of a long-term strategy.
However, development is not a passive shortcut to guaranteed returns. Planning delays, financing costs, construction overruns, weak demand, and poor execution can quickly damage a promising forecast. Long-term growth depends less on exciting renderings and more on disciplined due diligence, realistic assumptions, strong partners, and a clear plan for operating or selling the completed homes.
Why Housing Development Projects Can Support Long-Term Growth
Unlike a simple property purchase, a development project may create value at several stages. Land with uncertain use can become more valuable after planning permission. A carefully designed scheme can improve the commercial potential of a site. Construction converts that plan into a usable asset, while professional leasing and management can turn completed homes into a recurring income stream. Investors are therefore not relying on one source of return.
Multiple Return Drivers
Potential returns may come from development profit, rental income, long-term capital appreciation, refinancing, or the sale of a stabilised asset. In a build-to-sell scheme, the main objective is usually the margin between total development cost and completed sales value. In build-to-rent or private rented sector projects, value is also influenced by occupancy, rental growth, operating costs, and the yield that buyers apply to the finished income.
Real Assets and Inflation Exposure
Housing is a physical asset linked to land, labour, materials, and household demand. Rents and replacement costs may rise over time, which can offer some protection against inflation. That protection is not automatic, because higher inflation can also increase interest rates and construction costs. The strongest projects use conservative borrowing, sensible contingencies, and locations where people have a genuine reason to live.
Common Housing Development Models
Build-to-Sell Housing
Build-to-sell projects create houses or apartments for individual buyers. They can return capital relatively quickly after completion, but they depend heavily on mortgage availability, buyer confidence, pricing, and the speed of sales. Phased delivery can reduce risk by allowing the developer to test demand before releasing the entire scheme.
Build-to-Rent and Private Rented Sector Projects
Build-to-rent projects are designed for long-term rental operation rather than immediate unit-by-unit sale. Their investment case usually depends on stable occupancy, efficient management, attractive amenities, and predictable maintenance. They may suit investors seeking recurring income, but the operating platform must be strong because poor resident service can weaken retention and raise costs.
Purpose-Built Student Accommodation
Purpose-built student accommodation can benefit from concentrated demand near universities, especially where existing supply is limited. Investors should still examine enrolment trends, international student exposure, competing projects, transport links, room mix, nomination agreements, and the operator’s experience. A university name alone does not make every student scheme viable.
Affordable and Mixed-Tenure Housing
Affordable, social, shared-ownership, and mixed-tenure developments can combine social need with long-term contractual income or partnership structures. Returns may be steadier than speculative sales, although planning obligations, funding rules, delivery standards, and counterparty terms require close review. Mixed-tenure schemes can also broaden demand and improve community resilience.
The Main Drivers of Long-Term Investment Performance
Location and Local Demand
National averages are useful background, but housing is fundamentally local. Employment growth, universities, hospitals, transport investment, household formation, school quality, safety, and nearby supply all influence performance. Investors should study the exact catchment area, not just the city name. A strong city can contain weak micro-locations, while an overlooked regional centre may offer durable rental demand and lower land costs.
Supply Constraints and Planning Position
Limited housing supply can support values, but planning difficulty can also trap capital for years. Before investing, confirm the site’s legal title, planning status, access, utilities, flood risk, environmental constraints, affordable-housing obligations, infrastructure contributions, and likely approval timetable. Government viability guidance emphasises that affordable housing and infrastructure requirements should be reflected in land pricing and project deliverability.
Developer and Delivery Capability
The quality of the team often matters more than the attractiveness of the brochure. When reviewing a potential housing developer, examine completed projects, planning experience, contractor relationships, funding structures, defect management, and performance during difficult market conditions. Cassidy Group, for example, presents an end-to-end model covering land acquisition, planning, design, funding, delivery, and practical completion. Investors should treat any company website as a starting point and independently verify track record, ownership, finances, and project-specific claims.
Design, Energy Performance, and Future Operating Costs
A building that is expensive to heat, maintain, or insure may lose competitiveness over time. Efficient layouts, durable materials, good ventilation, low-carbon heating, renewable electricity, and realistic maintenance planning can strengthen long-term value. England’s Future Homes and Buildings Standards are scheduled to bring more demanding energy and low-carbon requirements into force in 2027, making forward-looking design increasingly important for projects entering the pipeline now.
Essential Due Diligence Before Investing
A development appraisal should be tested, not accepted at face value. Ask for a clear sources-and-uses schedule showing land, professional fees, planning costs, construction, finance, taxes, marketing, operating setup, and contingency. Confirm whether projected revenue is based on comparable evidence or optimistic assumptions. Then stress-test the model for delays, lower prices or rents, slower lease-up, higher interest, and construction inflation.
- Planning and land: verify title, access rights, planning conditions, section 106 or equivalent obligations, environmental surveys, utilities, and abnormal site costs.
- Financial structure: understand senior debt, mezzanine finance, investor equity, interest reserves, priority returns, profit sharing, and refinancing assumptions.
- Construction controls: review the contractor, contract type, fixed-price coverage, programme, insurance, warranties, performance security, and contingency budget.
- Market evidence: compare achievable rents or sales prices with genuine local transactions, competing supply, absorption rates, and the target customer’s affordability.
- Exit plan: identify who may buy the completed asset, what yield or valuation method is assumed, and what happens if the preferred sale or refinance is delayed.
- Governance: check reporting frequency, bank-account controls, valuation processes, conflicts of interest, approval rights, and procedures for cost overruns.
Major Risks and How Investors Can Manage Them
Planning and Programme Risk
Planning decisions, design revisions, utility connections, legal agreements, and contractor mobilisation can take longer than expected. Every delay adds professional fees and financing cost. Investors can reduce exposure by favouring sites with clearer planning positions, using milestone-based capital releases, and maintaining a programme that includes realistic approval and procurement periods.
Cost and Financing Risk
Development uses capital before it produces revenue. Rising labour, material, insurance, or borrowing costs can compress profit quickly. A meaningful contingency, independent quantity surveying, transparent procurement, and limits on leverage can protect the project. The appraisal should show the point at which the scheme stops meeting the investor’s minimum return rather than presenting only a best-case forecast.
Market and Exit Risk
House prices and rents move at different speeds across regions. The latest ONS data illustrate this variation: in June 2026, UK private rent inflation was 3.3% in the year to May, while average house prices were 3.8% higher in the year to April. Those figures are provisional and affected by timing and base effects, so they should not be treated as a guaranteed trend. A resilient project needs to work under more cautious assumptions.
Operational and Reputation Risk
For rental developments, practical completion is not the end of the investment. Poor maintenance, weak resident communication, safety failures, or badly controlled service charges can damage occupancy and asset value. Investors should review the operator’s systems, staffing, resident experience, maintenance reserve, compliance record, and data reporting before relying on long-term income projections.
How to Build a Long-Term Housing Development Strategy
Start by defining the investment objective. A family seeking stable income may prefer completed or near-completed rental housing, while an investor able to accept greater risk may participate earlier in the land, planning, or construction stage. Expected return should always be considered alongside liquidity, duration, leverage, tax, and the possibility of losing capital.
Use Staged Capital and Clear Milestones
Releasing capital after planning, pre-sales, debt approval, contractor appointment, or verified construction milestones can improve control. Independent monitoring surveyors and regular cost reports help confirm that work completed matches money drawn. Investors should know which events allow additional funding, restructuring, or a decision to stop.
Diversify Across Projects and Demand Types
Concentration can turn one local setback into a portfolio-wide problem. Diversification may involve different cities, developers, project stages, housing types, or income models. It should still be purposeful: owning several highly leveraged developments exposed to the same tenant group is not genuine diversification.
Track the Right Performance Indicators
Useful indicators include planning milestones, committed and forecast cost, construction progress, contingency remaining, debt drawdown, interest cover, pre-sales, leasing enquiries, occupancy, rent collection, incentives, operating cost per unit, defects, and resident retention. Reports should compare current performance with the original investment case and explain every material variance.
The 2026 UK Context: Opportunity Requires Selectivity
Demand for housing remains substantial, but investors should avoid assuming that every project will benefit equally. England recorded 208,600 net additional dwellings in 2024-25, down 6% from the previous year. At the same time, rent and house-price movements differ sharply by region. This combination can create opportunities in undersupplied markets, but it also makes local research and realistic absorption assumptions essential.
Planning contributions, affordable housing, infrastructure, building safety, and energy standards must be included early in the appraisal. Paying too much for land because future obligations were underestimated is one of the hardest mistakes to repair. Long-term growth begins with the acquisition price and continues through disciplined delivery, not with an optimistic exit valuation.
Questions to Ask Before Committing Capital
- What exact stage is the project at, and which major approvals remain outstanding?
- How were the sales values, rents, occupancy, and exit yield estimated?
- What happens to investor returns if completion is delayed by six or twelve months?
- Is the construction price fixed, and which risks remain outside the contract?
- How much contingency is available, and who can approve its use?
- What is the developer’s verified record on comparable projects?
- Who controls investor funds and monitors construction progress?
- What are the realistic exit options if market conditions weaken?
- How will the completed homes meet future energy, safety, and resident expectations?
- Can the investment be held longer than planned without forced selling?
Frequently Asked Questions
Are housing development projects suitable for beginners?
They can be complex for first-time investors because returns depend on planning, construction, finance, legal structure, and market timing. Beginners may prefer professionally managed funds, lower-risk completed assets, or projects with experienced partners and independent advice rather than investing directly in early-stage development.
How long does a housing development investment take?
The period can range from a few years for a straightforward construction-and-sale scheme to a decade or longer for land promotion and long-term rental ownership. Investors should plan for delays and avoid using capital that may be needed at short notice.
Conclusion
Housing development projects can support long-term investment growth because they combine land, value creation, housing demand, and potential income. The best opportunities are not necessarily the projects with the highest advertised return. They are the ones where land price, planning, design, construction, financing, demand, and exit strategy remain credible under pressure.
Investors should examine the full lifecycle, verify the developer’s evidence, stress-test the numbers, preserve cash reserves, and monitor delivery against clear milestones. For additional business and investment-focused educational content, visit aelftech.com. A patient, evidence-led approach cannot remove every risk, but it can make long-term growth more intentional and more defensible.
Leave a Reply